- FPL’s revenues and profits saw solid double-digit percentage increases in 1H23, helped by strong performances in the Singapore and Hospitality segments.
- We expect FPL to remain resilient amidst macro headwinds, driven by three of its segments: Industrial & Logistics, Retail, and Hospitality.
- We think FPL’s credit profile remains resilient, helped by its well-distributed debt maturity profile and its high percentage of fixed-rate debt.
- We recommend FPLSP 4.490% 16Sep2027 Corp (SGD) – Retail, a rare retail offering in the SGD space allowing investors to invest in denominations of SGD 1,000.
- Accredited investors can consider these two non-retail bonds: FPLSP 4.150% 23Feb2027 Corp (SGD) and FPLSP 3.000% 09Oct2028 Corp (SGD). Retail investors can also consider ASTLC 3.000% 18Mar2031 Corp (SGD) - Class A-1 – Retail for a retail alternative with decent yields.
About Frasers Property Limited (FPL)
Frasers Property Limited (“FPL”) is a leading real estate company headquartered in Singapore, with a diverse portfolio of properties primarily in Asia-Pacific and Europe. Its properties span a total of five asset classes: Industrial & Logistics, Commercial & Business Parks, Retail, Hospitality, and Residential.
FPL saw robust 1H23 results (as of 31 Mar 2023)
In its 1H23 results ended 31 Mar 2023, FPL saw its first-half revenues climb 16% year-on-year (“YoY”) to SGD 1.9b, while adjusted profit before interest and taxation (“PBIT”) also rose 30% to SGD 685m (Chart 1). Attributable profit saw solid growth to SGD 225.8m, representing an increase of 43%.
This strong performance was primarily due to: (i) a strong residential market in Singapore supporting residential prices and sales; and (ii) the easing of global COVID restrictions (especially in Asia) supporting the hospitality segment. Both the Singapore and Hospitality segments saw high PBIT growth rates of 97% and 128% respectively, with the Singapore segment particularly contributing to much of the group’s increase in PBIT (Table 1).
With this strong 1H23 showing, FPL appears to have turned the corner following COVID slowdown effects in 1H21. Over a longer 10-year time frame, FPL’s revenues have now grown 11.2% on a compounded annual growth rate (“CAGR”) basis, while its PBIT has risen 12.1%.
Chart 1: FPL saw strong growth in revenues and PBIT in 1H23
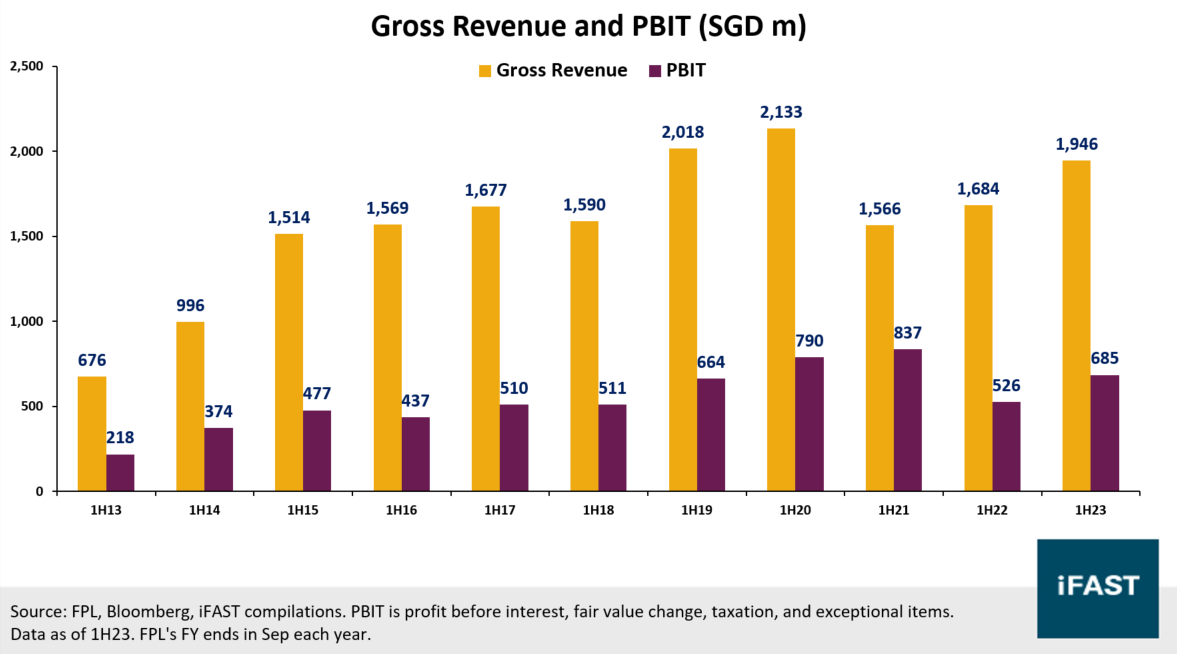
Table 1: Singapore and Hospitality segments saw large PBIT growth in 1H23
| Business Segment | 1H22 PBIT (SGD m) | 1H23 PBIT (SGD m) | YoY Change (%) |
| Singapore | 168.7 | 331.6 | 97% |
| Australia | 9.1 | 7.2 | -21% |
| Industrial | 207.3 | 181.7 | -12% |
| Hospitality | 28.0 | 63.9 | 128% |
| Thailand & Vietnam | 98.6 | 81.5 | -17% |
| Others (China / UK) | 47.2 | 46.4 | -2% |
| Corporate and Others | -32.8 | -27.4 | -16% |
| Source: FPL, Bloomberg, iFAST compilations. Data as of 1H23. FPL's FY ends in Sep each year. | |||
Outlook: FPL expected to remain resilient despite macro headwinds
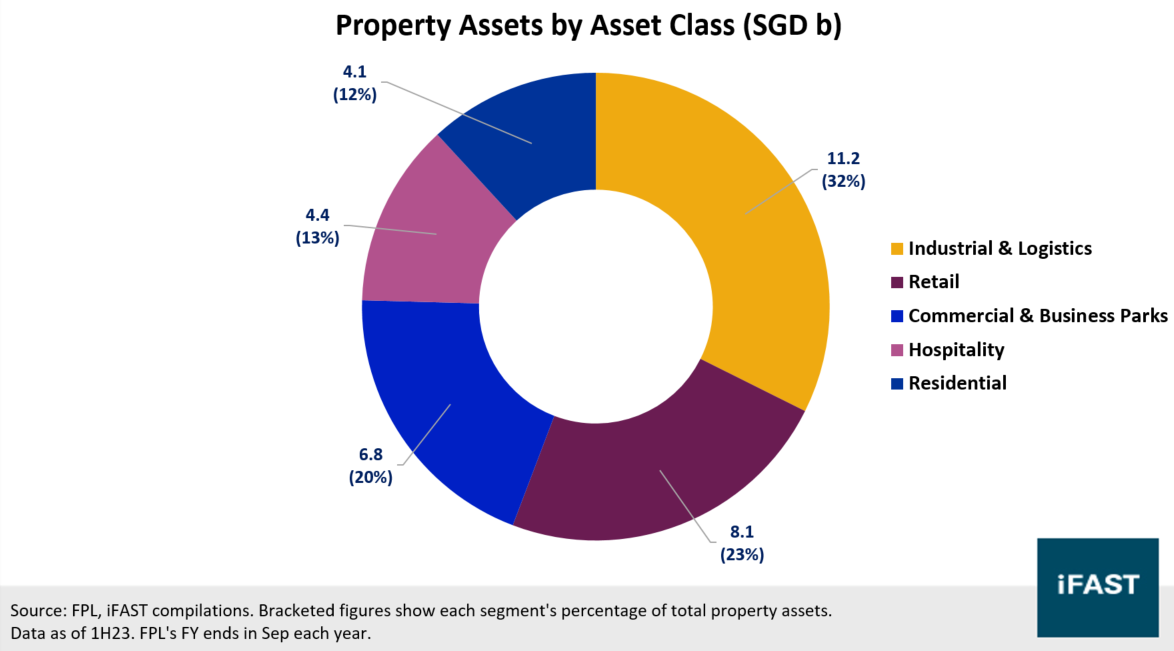
Within FPL’s five key asset classes (Chart 2), we have identified three segments (by asset class) which look particularly promising to us – Industrial & Logistics (“I&L”), Retail, and Hospitality – which we will elaborate on below.
Chart 2: FPL’s property assets by asset class
Industrial and Logistics
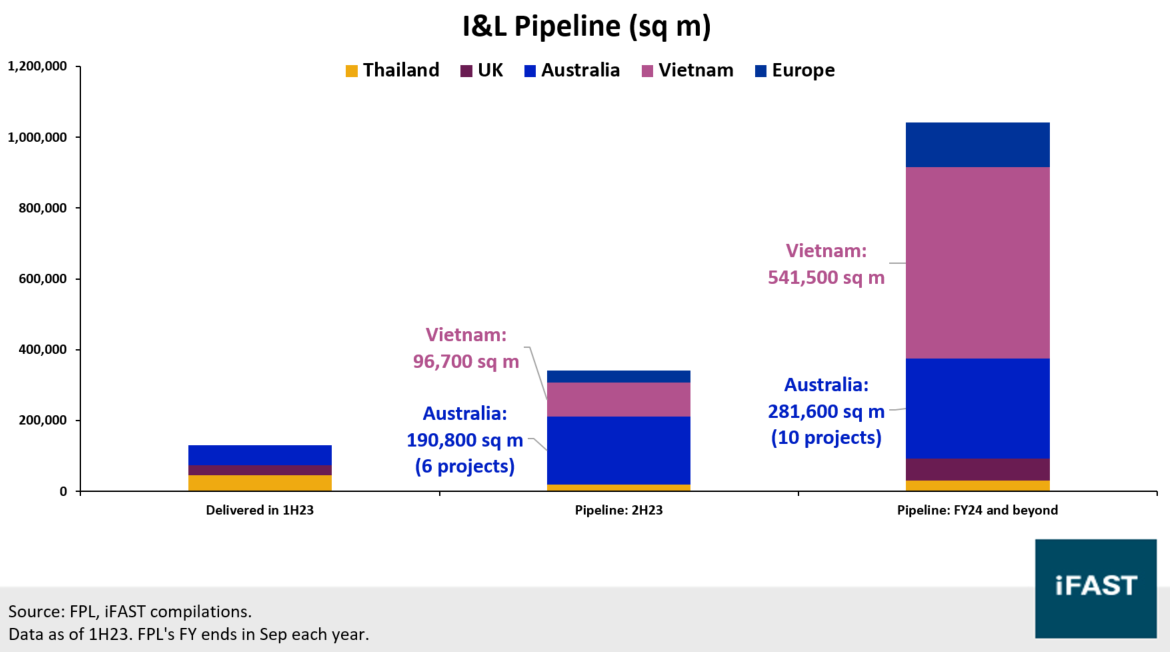
I&L is one of the largest segments of FPL, contributing to 28% of its total property assets. We like that it has a relatively healthy pipeline of looking ahead across different geographies (Chart 3), particularly in Australia and Vietnam.
On top of this healthy pipeline, we think industrial demand is likely to remain supported in the years ahead. Despite near-term macro headwinds, companies are likely to continue investing for the longer term, while Vietnam industrial properties in particular could benefit additionally from growing reshoring trends.
Chart 3: FPL continues to have a healthy I&L pipeline
Retail
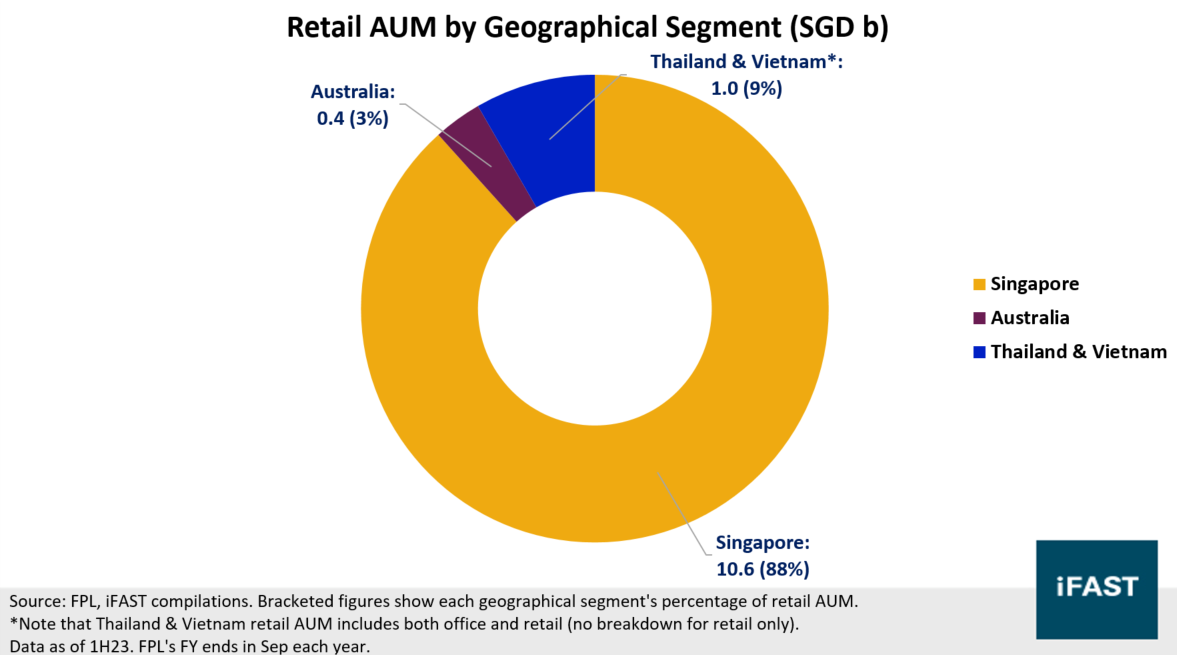
Retail is the second largest segment of FPL, contributing 23% of total property assets. Singapore accounts for a sizeable majority of its total retail AUM (Chart 4).
We expect Singapore retail property demand to also remain resilient. Despite macro headwinds, retail sales should broadly remain supported by a resilient domestic economy as well as tourism benefits, as the Asian continent reopens following the end of the COVID-19 pandemic, ultimately benefiting retail traffic.
Chart 4: Singapore accounts for a sizeable majority of total retail AUM
Hospitality
Within hospitality, both Asia-Pacific and Europe generally saw strong improvements in key metrics like average occupancy rate (“AOR”), average daily rate (“ADR”), and revenue per available room (“RevPAR”) (Table 2). The only exception was Europe ADR, which increased in local currency terms but saw a negative YoY change in SGD terms due to the appreciation of the SGD.
Looking ahead, we think hospitality could be a growth driver for FPL. We think that this segment could continue benefiting from the continued easing of border restrictions especially with the lifting of zero-COVID in China, which should result in higher corporate and leisure travel demand, both of which show little signs of moderating thus far.
Table 2: FPL Hospitality saw a strong performance in 3Q23
| Geography | FPL Hospitality Metrics | 3Q22 | 3Q23 | YoY Change |
| Asia Pacific | Average Occupancy Rate (%) (A1) | 56.2% | 75.9% | 19.7 pp |
| Average Daily Rate (SGD) (B1) | 167.1 | 225.2 | 34.8% | |
| Revenue Per Available Room (SGD) (A1 × B1) |
93.9 | 171.0 | 82.1% | |
| Europe | Average Occupancy Rate (%) (A2) | 67.4% | 76.5% | 9.1 pp |
| Average Daily Rate (SGD) (B2) | 239.4 | 228.6 | -4.5% | |
| Revenue Per Available Room (SGD) (A2 × B2) |
161.3 | 174.8 | 8.4% | |
| Source: FPL, iFAST compilations. Data as of 3Q23. FPL's FY ends in Sep each year. | ||||
Cash flow visibility supported by a solid outlook and a high percentage of recurring income
Given our analysis above, we expect FPL to remain resilient despite potential macro headwinds. We think that bondholders could also benefit from the strong cash flow visibility from FPL’s properties, particularly with 88% of its assets in recurring income asset classes.
Credit profile for FPL remains resilient
FPL’s nearer-term liquidity profile remains solid (Table 3) as of 1H23. Its operating cash flow ratio improved slightly due to a combination of larger operating cash flows and lower current liabilities, while its current ratio remained relatively steady at 1.32X in 1H23 (1H22: 1.33X). We note that it had a net cash outflow of almost SGD 1b over the past year primarily due to investing activities, but it maintains a relatively solid cash position of about SGD 2.9b overall, representing 7.3% of its total assets (SGD 2.6b in cash as of 3Q23).
Its longer-term credit profile also remains resilient – we highlight some key ratios below (Table 4) as of 3Q23. These three ratios generally remained fairly stable both on a QoQ and YoY basis. For instance, net debt / property assets climbed slightly to 40.7% with an increase in property asset values mitigating the slightly higher net debt levels. In addition, interest coverage also remained stable at 3X.
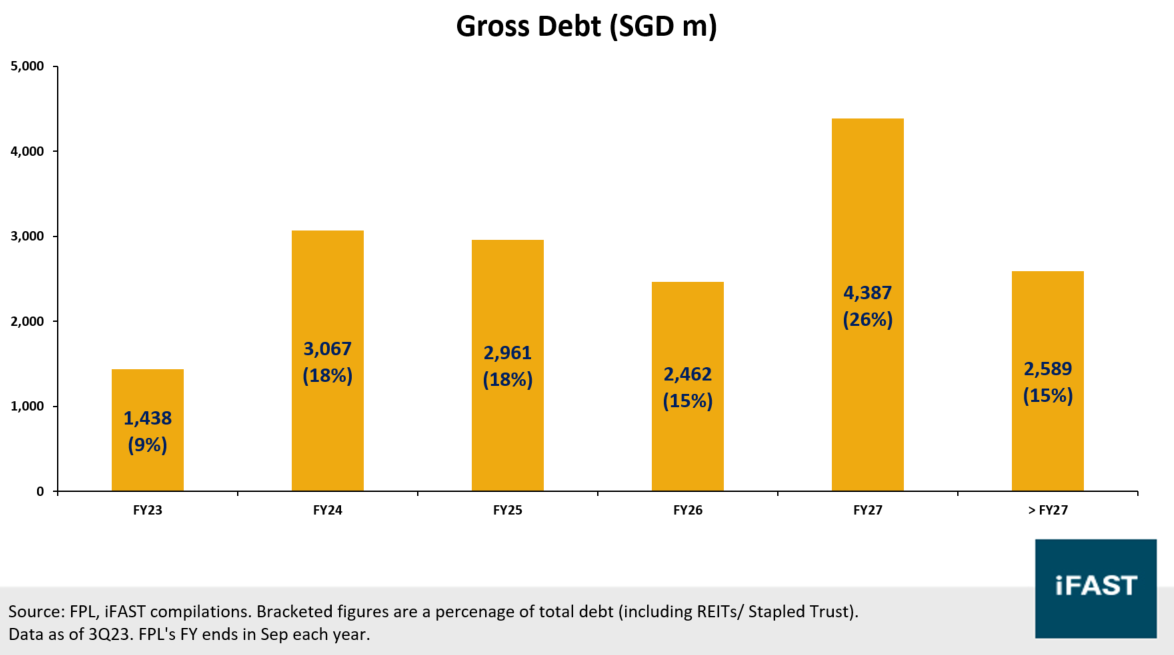
FPL’s overall debt profile remains solid. Its debt maturity profile is relatively well-distributed across the next few years, with its largest debt maturity year in FY27 (26% of total debt) (Chart 5). In addition, it has recently increased its percentage of fixed-rate debt from 74.5% (FY22) to 77.9% (1H23), which could be beneficial in a higher-for-longer rates environment.
Table 3: FPL’s nearer-term liquidity profile remains solid
| FPL's Financial Metrics | 1H22 | 1H23 |
| T12M Cash from Operations (SGD m) (A) | 1,450 | 1,574 |
| Current Assets (SGD m) (B) | 9,474 | 7,745 |
| Current Liabilities (SGD m) (C) | 7,098 | 5,859 |
| Cash & CE (SGD m) (D) | 3,913 | 2,927 |
| Operating Cash Flow Ratio (A / C) | 0.20 | 0.27 |
| Current Ratio (B / C) | 1.33 | 1.32 |
| Cash Ratio (D / C) | 0.55 | 0.50 |
| Source: FPL, Bloomberg, iFAST compilations, iFAST estimates. Data as of 1H23. FPL's FY ends in Sep each year. | ||
Table 4: FPL’s longer-term credit profile remains resilient
| FPL's Financial Metrics | 3Q22 | 3Q23 |
| Net Debt (SGD m) | 13,178.3 | 14,343.2 |
| Net Debt / Total Equity | 70.5% | 76.2% |
| Net Debt / Property Assets | 39.5% | 40.7% |
| Net Interest Coverage Ratio | 3 | 3 |
| Source: FPL, Bloomberg, iFAST compilations. Data as of 3Q23. FPL's FY ends in Sep each year. | ||
Chart 5: FPL’s overall debt profile remains solid
Recommendation
Looking ahead, we remain positive on FPL – we think that it can remain resilient amidst macro headwinds, with positive drivers in three of its segments: Industrial & Logistics (“I&L”), Retail, and Hospitality. We think FPLSP 4.490% 16Sep2027 Corp (SGD) – Retail looks attractive with a yield to maturity (“YTM”) of 4.209% (Table 5). This bond is a rare retail offering in the SGD space, allowing retail investors to invest in much smaller denominations of SGD 1,000 (compared to SGD 250,000 for non-retail bonds).
Accredited investors looking for some yield pick-up can also consider FPL’s non-retail 2027 and 2028 bonds: FPLSP 4.150% 23Feb2027 Corp (SGD) and FPLSP 3.000% 09Oct2028 Corp (SGD). While they can only be traded in larger denominations (SGD 250,000), they offer a slight yield pick-up over their retail counterpart (2027 bond: +14.1 basis points [“bps”], 2028 bond: +21.4 bps).
Compared to most other retail bonds, FPLSP 4.490% 16Sep2027 Corp (SGD) – Retail can potentially serve as a higher-risk higher-yield option for investors. This is because many outstanding retail bonds today are issued by quasi-sovereigns like Temasek, or government-linked companies like Singapore Airlines, both of which are less “risky” compared to FPL. One exception in terms of yields is ASTLC 3.000% 18Mar2031 Corp (SGD) - Class A-1 – Retail (YTW: 4.622%), though investors should note that this Astrea VI bond (i) sees structurally (very) different cash flows; (ii) has a lower coupon; and (iii) has a shorter maturity compared to FPL.
To summarise, FPLSP 4.490% 16Sep2027 Corp (SGD) – Retail is a rare retail offering in the SGD space which looks attractive in our opinion, especially for its higher yields compared to most other retail options. Accredited investors can also consider FPL’s non-retail 2027 and 2028 bonds FPLSP 4.150% 23Feb2027 Corp (SGD) and FPLSP 3.000% 09Oct2028 Corp (SGD) for a slight yield-pickup, while retail investors may consider the ASTLC 3.000% 18Mar2031 Corp (SGD) - Class A-1 – Retail for a retail alternative with decent yields.
Table 5: List of FPL and retail bonds (recommendations in blue)
| Bond Name | Maturity / Next Call Date (Years to Maturity / Next Call) |
Ask Price | Current Yield (%) | Yield to Worst (%) |
| FPLSP 4.490% 16Sep2027 Corp (SGD) - Retail |
16 Sep 2027 (4.1) |
101.042 | 4.444% | 4.209% |
| FPLSP 4.250% 21Apr2026 Corp (SGD) |
21 Apr 2026 (2.7) |
100.050 | 4.248% | 4.228% |
| FPLSP 4.150% 23Feb2027 Corp (SGD) |
23 Feb 2027 (3.5) |
99.350 | 4.177% | 4.350% |
| FPLSP 3.000% 09Oct2028 Corp (SGD) |
09 Oct 2028 (5.2) |
93.500 | 3.209% | 4.423% |
| TEMASE 2.700% 25Oct2023 Qsov (SGD) - Retail |
25 Oct 2023 (0.2) |
99.679 | 2.709% | 4.328% |
| SIASP 3.030% 28Mar2024 Corp (SGD) - Retail |
28 Mar 2024 (0.6) |
99.246 | 3.053% | 4.318% |
| ASTLC 3.850% 20Jun2029 Corp (SGD) - Class A-1 - Retail |
20 Jun 2024 (0.9) |
99.820 | 3.857% | 4.062% |
| ASTLC 3.000% 18Mar2031 Corp (SGD) - Class A-1 - Retail |
18 Mar 2026 (2.6) |
96.075 | 3.123% | 4.622% |
| TEMASE 1.800% 24Nov2026 Qsov (SGD) - Retail |
24 Nov 2026 (3.3) |
96.596 | 1.863% | 2.895% |
| ASTLC 4.125% 27May2032 Corp (SGD) - Class A-1 - Retail |
27 May 2027 (3.8) |
100.207 | 4.116% | 4.064% |
| Source: Bloomberg, Bondsupermart, iFAST compilations. Data as of 10 Aug 2023. | ||||
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in TEMASE 2.700% 25Oct2023 Qsov (SGD) - Retail. The analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!